Executive Summary: A property transaction is the legal process by which ownership or rights in real estate move from one person to another: by sale, gift, settlement, partition, release or inheritance. Five core statutes regulate property transactions across Tamil Nadu. The Transfer of Property Act and the Registration Act govern the execution and legal validity of deeds. State amendments to the Indian Stamp Act enforce appropriate stamp duties, while the Income Tax Act addresses tax obligations on transactions. Finally, authorities apply the Foreign Exchange Management Act to monitor all real estate transfers involving non-resident individuals.
Key Takeaway: Most property disputes begin with a weak document, an unchecked title or an unregistered deed. A sale deed must be registered, stamp duty is charged on the higher of the price and the guideline value, and tax is payable by the seller on any gain. Check title first, document everything, register on time, and plan the tax before signing.
Rates and section numbers change by notification and by Finance Act. The Income-tax Act, 2025 has been in force since 1 April 2026 and renumbers many sections; this guide uses the familiar section numbers. Confirm current figures with your advocate or chartered accountant.
1. What Is a Property Transaction?
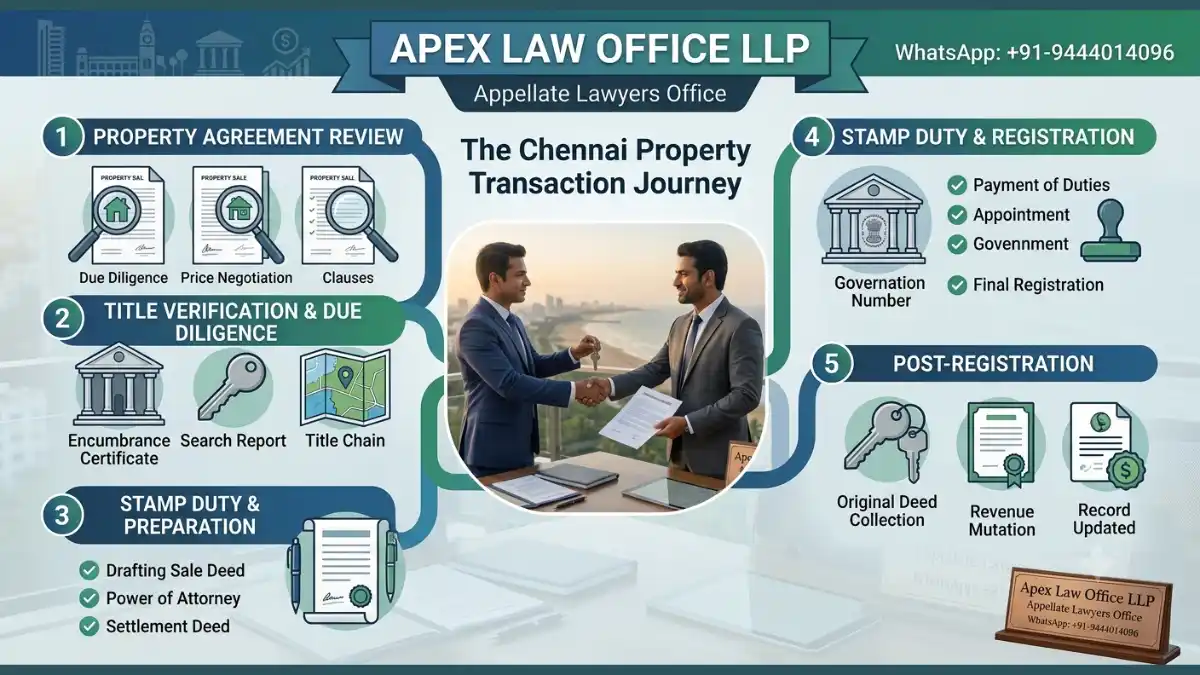
A property transaction typically moves through these stages: negotiation, written agreement, title verification (due diligence), execution of the deed, registration at the Sub-Registrar office, and post-registration steps such as patta transfer, property tax and utility changes.
Key features
- Registration is compulsory for sale, gift and certain other documents (section 17, Registration Act). A deed must be presented for registration within 4 months of execution (section 23).
- Writing is essential. Immovable property of value above ₹100 can be sold only by a registered instrument (section 54, Transfer of Property Act).
- Taxes apply. Stamp duty and registration fee are paid on the deed. Capital gains tax arises for the seller.
- Documents matter. Title documents, encumbrance certificate, patta, chitta and tax receipts decide how safe a transaction is.
2. Types of Property Transactions
| Transaction | Parties | Document | Registration | Stamp duty (indicative) |
|---|---|---|---|---|
| Sale | Seller and buyer | Sale deed | Compulsory | 7% plus registration fee (about 4%) |
| Gift | Donor and donee | Gift deed | Compulsory | Concessional for specified family members; full rate otherwise |
| Settlement | Settlor and beneficiary | Settlement deed | Compulsory | Concessional for family members |
| Partition | Co-owners | Partition deed | Compulsory | Concessional for family members |
| Release | One co-owner to others | Release deed | Compulsory | Concessional for family members |
| Inheritance | Heirs of deceased owner | Legal heir certificate, probate, family arrangement | As applicable | As applicable |
Stamp duty is payable on the higher of the consideration and the guideline value. Rates are indicative and should be confirmed on TNREGINET or with the Sub-Registrar before execution.
3. Buying Property
Step 1: Search and negotiation (1–3 weeks)
Inspect the property, confirm who is the actual owner and agree the price.
Step 2: Agreement of sale (1–2 days)
The agreement records the price, advance paid, payment schedule, possession date and the time allowed to complete the sale deed. It carries a nominal stamp duty and is generally unregistered, but if possession is handed over the stamp duty position changes. Take advice before signing.
Step 3: Due diligence (2–4 weeks)
- Obtain the encumbrance certificate (EC) for at least 30 years where records are available
- Examine the chain of title documents and the parent document
- Check patta, chitta, FMB sketch and property tax receipts
- Verify approvals: DTCP or CMDA layout approval, building plan and completion certificate
- Check pending litigation and attachments
Step 4: Payment and execution (1 day)
Pay through banking channels. The seller executes the sale deed on stamp paper of the correct value.
Step 5: Registration (1 day to 1 week)
Both parties appear before the Sub-Registrar with identity proofs and witnesses. Slots can be booked online on TNREGINET.
Step 6: After registration (1–3 weeks)
Apply for patta transfer, change property tax and electricity or water connections, and keep certified copies safely.
Indicative cost on a ₹50 lakh purchase: stamp duty 7% (₹3.5 lakh), registration fee about 4% (₹2 lakh), plus advocate and other charges. The total is therefore about ₹5.5 to ₹6 lakh. Confirm the current registration fee on TNREGINET.
4. Selling Property
The seller must prove clear title, discharge any loan, hand over original documents against full payment and cooperate in registration.
Tax for the seller
- Long-term capital gain (property held more than 24 months), for sales on or after 23 July 2024: 12.5% without indexation, plus surcharge and 4% cess. Resident individuals and HUFs who acquired the property before 23 July 2024 may choose 20% with indexation.
- Short-term capital gain (held 24 months or less): taxed at the seller’s normal slab rates.
- Exemptions: Sections 54, 54EC and 54F allow relief when gains or proceeds are reinvested as the law requires.
- TDS when the buyer is paying a resident seller: the buyer deducts 1% of the price under section 194-IA where the price is ₹50 lakh or more.
- TDS when the seller is an NRI: section 195 applies on the full price (see section 9).
Illustration (resident seller, simplified): purchase cost ₹30 lakh, sale price ₹80 lakh, long-term gain ₹50 lakh, tax at 12.5% = ₹6.25 lakh plus cess (and surcharge, if any). If the property was bought before 23 July 2024, compare the 20% with indexation option.
5. Gift and Settlement
A gift is a voluntary transfer without consideration. A settlement deed is commonly used within families, often with conditions, for example life interest to the settlor.
Legal requirements
- Written, signed by the donor, accepted by the donee, attested by at least two witnesses, and registered
- The donor must have a clear title and capacity, and the gift must be of existing property
Stamp duty and registration
- For gifts, settlements, releases and partitions among specified close family members, Tamil Nadu charges concessional rates, reported at about 1% stamp duty and 1% registration fee, subject to caps. Gifts to others attract the full sale deed rates. Confirm the current notification before execution.
Income tax on gifts
- There is no separate gift tax in India. However, under section 56(2)(x), gifts of immovable property received without or for inadequate consideration (above ₹50,000) are taxable in the hands of the recipient, unless received from a relative as defined in the Act, on marriage, or by inheritance or will.
- A donor does not treat a gift as a sale for tax purposes. However, when the recipient later sells the property, tax authorities calculate capital gains by carrying over the original owner’s purchase cost and holding period.
Revocation: A donor must be certain of their decision before signing a gift deed because the law prohibits unilateral cancellation once registration occurs. Courts permit cancellation only under specific legal grounds, such as fraud, coercion, or undue influence.
6. Partition and Release
Voluntary partition among co-owners or family members is done by a registered partition deed. All co-owners must agree on the shares and the demarcation of each portion. Concessional stamp duty applies to specified family members.
Release deed: One co-owner gives up their share to the other co-owners. A release in favour of a stranger can be treated as a transfer and charged accordingly.
Forced partition: If co-owners cannot agree, any co-owner may file a partition suit in the civil court. The court appoints a commissioner to divide the property and passes a final decree. These suits can take several years. Hindu women have equal coparcenary rights after the 2005 amendment to the Hindu Succession Act.
7. Inherited Property
Inheriting property is not taxed. Before selling, heirship should be documented.
- Where there is no will: a legal heir certificate from the Tahsildar, supported by a family tree and, where possible, a registered family arrangement. If heirs disagree, a civil court decides.
- Where there is a will: probate or letters of administration where required. For wills made in the City of Chennai, probate is generally mandatory.
- A succession certificate under the Indian Succession Act is mainly used for debts and securities, not for immovable property.
Tax on a later sale: The heir takes over the previous owner’s cost of acquisition and holding period (section 49). India has no step-up to the market value at the date of death. For property acquired before 1 April 2001, the fair market value on that date can be adopted as cost. See our detailed article on selling inherited property.
8. Costs and Taxation
Indicative transaction costs (₹50 lakh sale deed)
| Item | Rate | Amount |
|---|---|---|
| Stamp duty | 7% | ₹3.5 lakh |
| Registration fee | about 4% | ₹2 lakh |
| Advocate, document and verification charges | Varies | ₹20,000 to ₹80,000 |
Family deeds (gift, settlement, release, partition among specified relatives): reported at about 1% stamp duty and 1% registration fee, subject to caps.
Capital gains (for the seller)
| Situation | Rate |
|---|---|
| Long-term (more than 24 months), sale on or after 23 July 2024 | 12.5% without indexation, plus surcharge and cess |
| Resident, acquired before 23 July 2024 | May choose 20% with indexation, whichever is lower |
| Short-term (24 months or less) | Normal slab rates |
TDS on sale
| Seller | Section | Rate |
|---|---|---|
| Resident (price ₹50 lakh or more) | 194-IA | 1% of the price |
| NRI | 195 | 12.5% plus surcharge and cess on long-term gain, slab rates on short-term gain, on the full price; can be reduced by a Form 13 certificate |
9. NRI Property Transactions
Non-Resident Indians (NRIs) and Persons of Indian Origin (PIOs) purchase residential and commercial properties in India under Foreign Exchange Management Act (FEMA) guidelines. These individuals freely sell, gift, or inherit real estate, subject to statutory regulations. However, federal laws prohibit non-residents from acquiring agricultural land, plantation property, or farmhouses through direct purchase. Foreign investors must therefore sell any inherited agricultural holdings exclusively to resident Indian citizens.
Buying
- Payment must come through banking channels from NRE, NRO or FCNR(B) accounts or inward remittance
- A registered Power of Attorney, executed abroad, notarised and apostilled (or consular attested), allows a trusted person to sign
- Obtain PAN, and ensure the Power of Attorney is stamped and registered as required in Tamil Nadu
Selling
- The buyer deducts TDS under section 195 on the full price. The NRI can apply for a lower-deduction certificate (Form 13) before the sale
- An NRI deposits sale proceeds directly into their Non-Resident Ordinary (NRO) account. An authorized dealer bank then permits the repatriation of up to USD 1 million per financial year upon receiving Forms 15CA and 15CB.
- File the Indian income tax return and claim credit for the TDS
Inheriting
- NRIs have the same succession rights as resident heirs. A registered Power of Attorney can help a local representative obtain certificates and complete formalities
10. When to Engage an Advocate
- Any purchase or sale: title search, deed drafting, registration support
- NRI transactions: Power of Attorney, FEMA and tax coordination
- Inherited property or disputes among heirs
- Partition, release or family settlement
- Properties with loans, litigation, unclear patta or missing parent documents
A basic gift or an agreed partition among relatives may be simple, but even then a registered, properly drafted document avoids later disputes.
11. Frequently Asked Questions
FAQ 1: How long does a property transaction take?
Answer: A resident sale usually takes 6 to 12 weeks from agreement to registration, depending on title checks and loan processing. Gift and family deeds can be done within a few weeks. NRI transactions and inheritance can take longer because of Power of Attorney, tax and heirship formalities.
FAQ 2: What stamp duty applies to a sale deed in Tamil Nadu?
Answer: Stamp duty is 7% on the higher of the price and the guideline value, with a registration fee in addition (about 4% under current notifications). Family gifts, settlements, releases and partitions attract concessional rates. Confirm current rates on TNREGINET before execution.
FAQ 3: Can an NRI buy property without visiting India?
Answer: Yes, through a properly executed and registered Power of Attorney, subject to identity verification and FEMA conditions. Payments must come through banking channels.
FAQ 4: What is the difference between an agreement of sale and a sale deed?
Answer: An agreement of sale is a contract to sell in the future and does not transfer ownership. The sale deed, once registered, transfers ownership.
FAQ 5: Is tax payable on inherited property?
Answer: There is no inheritance tax in India and inheriting is not taxable. Tax arises on a later sale. The heir takes over the previous owner’s cost and holding period.
FAQ 6: What if the sale deed is not registered in time?
Answer: An executing party must present a document for registration within four months of execution under Section 23 of the Registration Act. The registering authority accepts a late submission only after levying a fine and enforcing specific conditions. Additionally, a buyer receives no valid title from an unregistered sale deed. Courts therefore enforce strict compliance with registration timelines to protect property rights.
FAQ 7: Is property tax the same in all Tamil Nadu cities?
Answer: No. Property tax is levied by the local body (corporation, municipality or panchayat) and varies by location, usage and area. Pay it regularly because arrears can affect mutation and sale.
FAQ 8: Can co-owners partition property without going to court?
Answer: Yes. If all co-owners agree, a registered partition deed divides the property. If any co-owner refuses, a civil suit for partition is needed.
Related Articles
- Sale Deed Registration in Chennai: Complete Legal Guide
- NRI Buying Property in Chennai: Complete Legal Guide
- Inherited Property Sale in Tamil Nadu: Complete Legal Guide
- Property Title Due Diligence in Tamil Nadu: Complete Verification Guide
Need Legal Help?
Apex Law Office LLP assists with title verification, agreements, deeds, registration, NRI transactions, inherited property and property disputes in Tamil Nadu.
This article is for general information and is not legal or tax advice.


